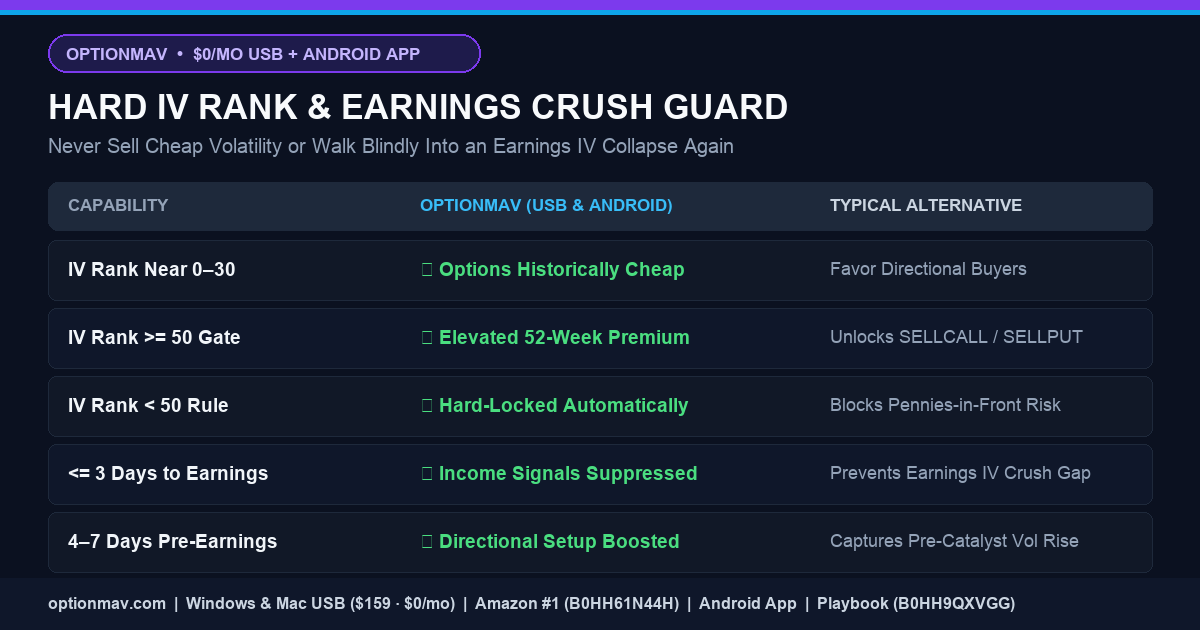
Direct Answer: Seeing “Implied Volatility: 34%” on an option chain tells you nothing by itself—34% IV is sky-high for a utility ETF and rock-bottom for a high-beta semiconductor stock. OptionMAV computes a rolling 52-week IV Rank (0–100) for every US stock and ETF on your watchlist and enforces two non-negotiable safety gates: (1) Income setups (SELLCALL / SELLPUT) are hard-locked whenever IV Rank is below 50, and (2) Income setups are automatically suppressed within 3 days of earnings so you never get blindsided by an overnight earnings gap.
Why Raw Implied Volatility Misleads Retail Traders
Two expensive traps wipe out self-directed options accounts every earnings season:
- Buying overpriced calls or puts right before earnings: The stock moves 3% in your favor the next morning, yet your call option loses 45% because Implied Volatility collapsed at the opening bell.
- Selling options when IV Rank is 15: You collect tiny premium with terrible reward-to-risk, then watch a single volatility expansion double the contract price against you.
How OptionMAV’s Hard IV Rank ≥ 50 & Earnings Gates Protect You
- Rolling 52-Week IV Rank (0 to 100): Measures exactly where today’s implied volatility sits relative to that specific ticker’s past 12 months. Near 0 means options are at their cheapest all year (favoring directional buyers); near 100 means options are at peak richness (favoring premium sellers).
- Unbreakable IV Rank ≥ 50 Income Lock: Income mode is off by default for safety. Even when toggled on, if a ticker’s IV Rank is 49 or lower,
SELLCALLandSELLPUTwill not fire—full stop. - Automatic 3-Day Pre-Earnings Suppression: On every scan cycle, OptionMAV checks upcoming earnings dates. Within 3 days of an announcement, income signals are suppressed automatically and labeled right on the card.
- 4–7 Day Pre-Catalyst Directional Window: When a directional
BUYCALLorBUYPUTfires 4 to 7 days ahead of earnings—historically the sweet spot for pre-event volatility expansion—OptionMAV boosts setup conviction accordingly. - 1σ Expected Move Bracket: Every signal card overlays the market-implied 1-standard-deviation price range at expiration, showing premium sellers at a glance whether their ~0.20–0.25 Delta strike sits safely outside the expected move.
For a complete chapter-by-chapter decision framework on decoding IV Rank across VIX regimes, read Chapter 3 of our official 201-page guide, The Greeks Are Not Your Enemy: The OptionMAV Playbook on Amazon.
The 3 Categories of Retail Options Software (How to Choose the Right Tool)
Self-directed US stock & ETF options tools fall into three distinct architectural categories:
Helpful for drawing P&L curves after you already picked a ticker and strike—but offers zero automated market-wide contract discovery, zero hard IV Rank gating, and zero automated exit monitoring.
Streams dark-pool and sweep alerts ($576–$1,788/yr) without revealing whether an institution is hedging 500,000 shares of stock—leaving retail traders chasing noisy premium with no exit plan.
Computes all 8 Black-Scholes-Merton Greeks locally, enforces a hard 52-week IV Rank ≥ 50 income gate + 3-day pre-earnings guard, toggles 1-click vertical credit/debit spreads, and monitors exits with $0/mo ongoing USB fees.
Choose Your OptionMAV Setup — $0/mo Physical USB, Android App & Free Calculator
Screen US stock & ETF options contracts with all 8 Black-Scholes-Merton Greeks, rolling 52-week IV Rank (≥50 income gating), 3-day pre-earnings IV-crush protection, and one-toggle vertical credit/debit spreads—without surrendering your watchlist to a $200/month cloud platform.
Frequently Asked Questions
What is the difference between Implied Volatility (IV) and IV Rank in OptionMAV?
Implied Volatility is the annualized expected move priced into an option right now, while IV Rank (0–100) compares today’s IV against that specific stock’s highest and lowest IV over the past 52 weeks so you immediately know whether contracts are historically cheap or expensive.
Why does OptionMAV block SELLCALL and SELLPUT below IV Rank 50?
Selling options when implied volatility is in the bottom half of its annual range underpays sellers for tail risk and exposes positions to sharp losses if volatility normalizes upward. Locking income signals until IV Rank >= 50 enforces institutional premium-selling discipline automatically.
Continue Exploring the OptionMAV Options Research Library
- Best AI Options Screener Without a Monthly Subscription: OptionMAV $159 USB & Android App vs. $200/Mo Cloud Tools
- Vertical Credit & Debit Spread Screener: Find Defined-Risk Options Setups Without Level 4 Naked Margin
- Covered Call & Cash-Secured Put Screener: Run the Wheel Strategy Without Linking Your Brokerage Account
- Options Greeks Explained in Plain English (Delta, Theta, Vega, Vanna & Charm): The OptionMAV Playbook
- Stop Watching Winning Options Decay to Zero: Automated Options Exit Alerts, Roll Guidance & Android Portfolio Tracking
- OptionStrat Alternative: Visual Payoff Calculator vs. OptionMAV’s $0/Mo AI Options Screener & Spread Analyzer
- Unusual Whales & Cheddar Flow Alternative: Why Retail Traders Ditch Noisy Dark-Pool Sweeps for Defined-Risk AI Setups
- Market Chameleon & Barchart Options Screener Alternative: Own 52-Week IV Rank & Wheel Screening on a $159 USB
- Why Your Call Option Lost Money When the Stock Went Up: Plain-English Guide to Earnings IV Crush & the 3-Day Guard
- Weekly vs. Swing vs. LEAPs Options: Complete Delta (0.20 vs. 0.50) & DTE Selection Matrix for Retail Traders
- Why DIY Options Spreadsheets & Weekend Scripts Break Down—And How a Turnkey $159 USB Solves All 8 Greeks Locally
Interactive Tools & Official Channels: 🧮 Free Spread & IV Rank Calculator · 📘 201-Page Greeks Playbook ($12.99) · ⚡ OptionMAV USB ($159 · $0/mo) · 🛒 Amazon US (#1 Ranked) · 📱 OptionMAV Android App · All 12 Guides