The Greeks Are Not Your Enemy: The OptionMAV Playbook
Stop guessing why your option lost money when the stock moved your way. Written by the Atlanta, GA OptionMAV engineering team (325% funded on Kickstarter), this 201-page field manual translates all 8 Black-Scholes-Merton Greeks, 52-week IV Rank, and defined-risk spreads into plain English.
Inside the Playbook
- All 8 Greeks Decoded: Delta, Gamma, Theta, Vega, Rho + Vanna, Charm & Vomma
- Strike Sweet Spots: Why buyers target 0.40–0.55 Δ and income sellers target 0.20–0.25 Δ
- 52-Week IV Rank & Earnings Rules: Hard IVR ≥ 50 gate & 3-day pre-earnings guard
- The 30-Second Card Protocol: Read any setup top-to-bottom without paralysis
- 9 Tear-Out Cheat Sheets: VIX stress matrices, vertical spreads & Wheel sizing
Direct Answer: The Greeks Are Not Your Enemy: The OptionMAV Playbook (201 pages, Amazon ASIN B0HH9QXVGG, $12.99 Kindle / $29.99 Paperback) is the official plain-English companion manual to the $159 OptionMAV USB (Windows & Mac) and OptionMAV Android App. It teaches everyday retail traders how to read all 8 options Greeks, avoid pre-earnings IV crush, and structure defined-risk vertical spreads in 30 seconds.
Interactive 8-Greeks Reference Matrix (First-Order + Second-Order)
Filter between the 5 standard Greeks and the 3 institutional second-order Greeks computed locally from first principles on every OptionMAV signal card:
| Greek | Order | Plain-English Trader Question Answered | OptionMAV Signal Card Benchmark |
|---|---|---|---|
| Delta (Δ) | First-Order | How many cents does my option gain or lose per $1 move in the stock? | 0.40–0.55 Δ for BUYCALL/BUYPUT · 0.20–0.25 Δ (~1σ OTM) for SELLCALL/SELLPUT |
| Gamma (Γ) | First-Order | How fast does my Delta accelerate as the stock approaches my strike? | Highest convexity on Weekly (1–14 DTE); smoother risk curve on Swing (15–60 DTE) |
| Theta (Θ) | First-Order | How many dollars per day does time decay cost buyers (or pay sellers)? | Sellers harvest the 20–45 DTE decay curve (80% decay exit target); buyers exit before late-DTE cliff |
| Vega (ν) | First-Order | How much does my option price change per 1% shift in Implied Volatility? | Paired with rolling 52-week IV Rank so buyers avoid peak-IV crush and sellers demand IVR ≥ 50 |
| Rho (ρ) | First-Order | How sensitive is my long-dated contract to interest-rate changes? | Tracked automatically on LEAPs (180–730 DTE) stock-replacement contracts |
| Vanna | Second-Order | How does my Delta change when Implied Volatility shifts—even if price stands still? | Exposes volatility-driven dealer hedging tailwinds and warns against post-event Delta shrinkage |
| Charm | Second-Order | How much Delta bleeds away overnight and over weekends purely from time passing? | Critical pre-weekend check on Weekly OTM options so Monday morning doesn’t open sluggish |
| Vomma | Second-Order | How fast does Vega itself accelerate during sudden volatility spikes? | Measures convexity in fast-moving macro or short-squeeze regimes |
The 30-Second OptionMAV Signal Card Reading Protocol
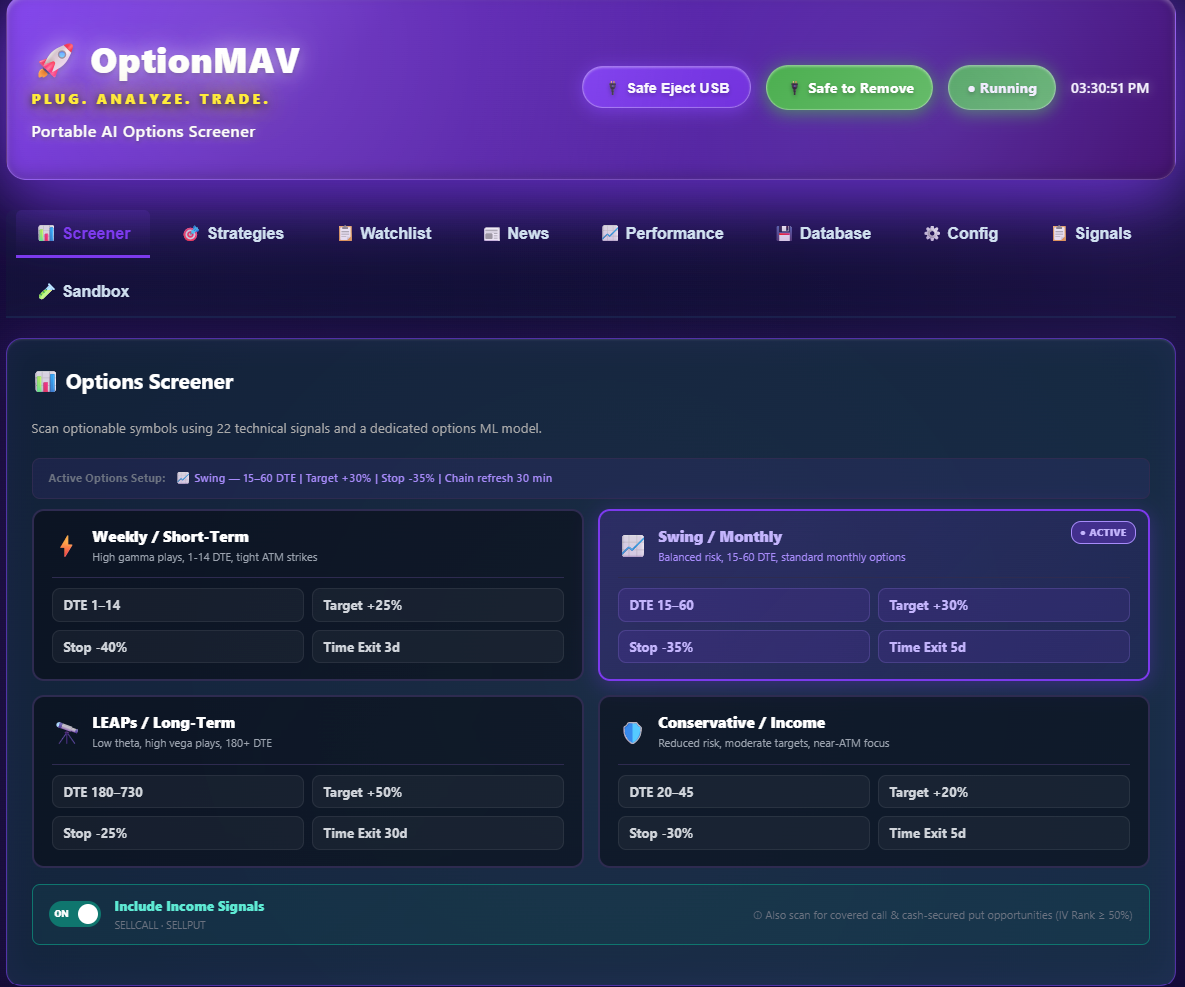
1. Direction & Active Profile
Confirm whether the card is directional (BUYCALL / BUYPUT) or income (SELLCALL / SELLPUT) and matches your Weekly, Swing, LEAPs, or Conservative horizon.
2. 52-Week IV Rank & Earnings
Verify IV Rank (0–100) supports buying vs. selling volatility and confirm no earnings binary event violates the 3-day guard.
3. Strike, Delta & 1σ Bracket
Inspect the real exchange-listed strike against the 1-standard-deviation expected move bracket and buyer/seller Delta sweet spot.
4. Vanna, Charm & Squeeze Badge
Check second-order Greeks for overnight/volatility drag and inspect the US Short Squeeze badge (Gray / Amber / Red) before selling calls.
5. Single-Leg vs. Spread & Funded Check
Toggle Vertical Spread Mode to compare capped Max Loss, Breakeven, Covered Call / CSP tags, and your local Funded ✅ badge.
6. Exit Target & Roll Policy
Track premium-calibrated stop, profit-target, and roll windows via OptionMAV USB private push channels or the Android Portfolio Exit Tracker.
Choose Your OptionMAV Setup — $0/mo Physical USB, Android App & Free Calculator
Screen US stock & ETF options contracts with all 8 Black-Scholes-Merton Greeks, rolling 52-week IV Rank (≥50 income gating), 3-day pre-earnings IV-crush protection, and one-toggle vertical credit/debit spreads—without surrendering your watchlist to a $200/month cloud platform.
Frequently Asked Questions
What is ‘The Greeks Are Not Your Enemy: The OptionMAV Playbook’ about?
Published by TradeMAV LLC (201 pages, ASIN B0HH9QXVGG), ‘The Greeks Are Not Your Enemy: The OptionMAV Playbook’ translates all 8 Black-Scholes-Merton Greeks—Delta, Gamma, Theta, Vega, Rho, Vanna, Charm, and Vomma—plus rolling 52-week IV Rank, the 3-day pre-earnings guard, vertical spreads, Covered Calls, Cash-Secured Puts, and the 30-second Signal Card Reading Protocol into plain English for everyday US stock and ETF options traders.
Do I need to own the OptionMAV USB or Android App to benefit from the book?
No. Every Greek rule, 52-week IV Rank threshold, buyer vs. seller Delta zone (0.40–0.55 vs. 0.20–0.25), and 9 cheat-sheet appendices apply directly to any US stock or ETF options chain. If you also use the $159 OptionMAV USB (Windows & Mac) or OptionMAV Android App, every chapter maps 1-to-1 to the exact fields on your signal card.
Where can I buy the OptionMAV Playbook and in what formats?
The official 201-page book is available worldwide on Amazon (amazon.com/dp/B0HH9QXVGG) in instant Kindle eBook format ($12.99) and full-size print Paperback ($29.99).