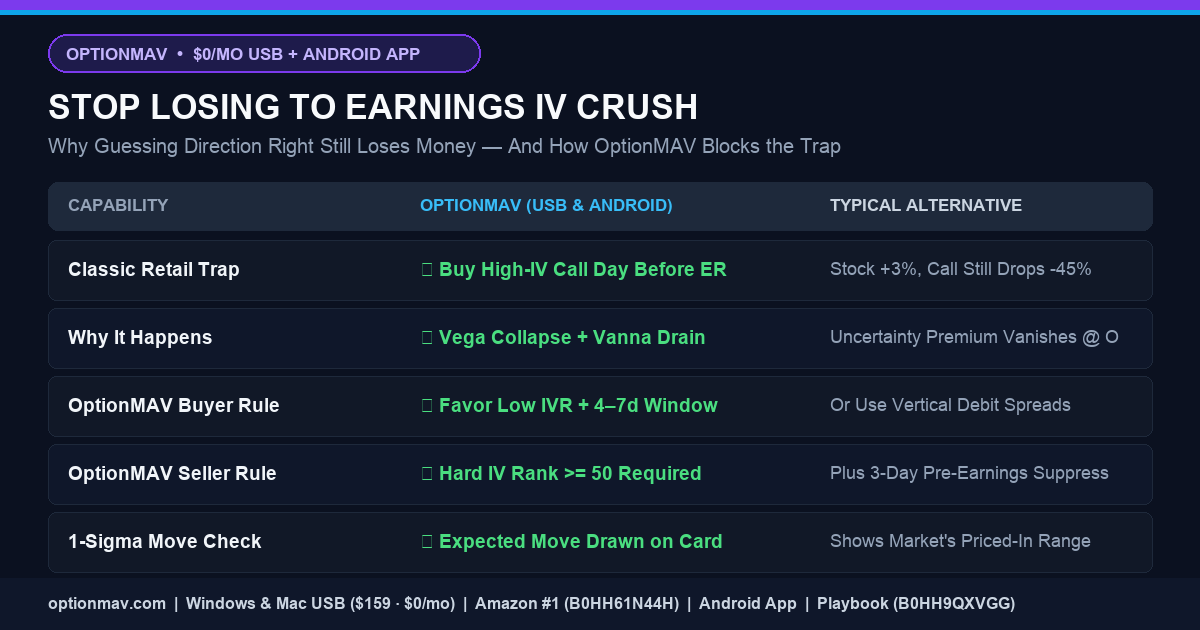
Direct Answer: When a stock rises +3% after earnings yet your call option drops −45%, you were hit by Implied Volatility (IV) crush: the stock moved less than the market’s priced-in Expected Move, so overnight Vega collapse and Vanna decay wiped out more extrinsic value than Delta gained. OptionMAV prevents this with rolling 52-week IV Rank, 1σ Expected Move brackets, 1-tap Vertical Spreads, and an automatic 3-Day Pre-Earnings Guard.
Real Dollar Anatomy of an Earnings IV Crush
Imagine a $200 tech stock reporting earnings after the close today. Because nobody knows the headline numbers yet, market makers inflate Weekly option Implied Volatility from 32% to 78% (IV Rank 94), pricing in a ±$14 (±7%) overnight move:
| Moment in Time | Stock Price | Implied Volatility | $205 Weekly Call Price | What Happened Under the Hood |
|---|---|---|---|---|
| 3:55 PM Pre-Earnings | $200.00 | 78% (IV Rank 94) | $6.40 ($640/contract) | 100% of your $640 is inflated extrinsic uncertainty premium (Delta 0.42, Vega $0.14). |
| 9:31 AM Next Morning | $206.00 (+3.0%) | 34% (−44 pts!) | $3.50 (−45.3% loss!) | Delta added ~$2.52, but the 44-point IV collapse multiplied by Vega + Vanna erased −$5.42! |
4 Mechanical Rules OptionMAV Uses so You Never Step Into That Trap
- Check 52-Week IV Rank First (Test Any Ticker in Our Free Calculator): Know immediately whether today’s IV sits at 15 (cheap for directional buyers) or 92 (dangerously inflated for naked single-leg buyers).
- Compare Your Target Against the 1σ Expected Move Bracket: Every OptionMAV signal card plots the market-implied 1-standard-deviation range at expiration so you see what move is already priced in.
- Flip Single-Leg Buys Into Call/Put Debit Spreads When IV Is Elevated: Selling an OTM call against your long call offsets a large chunk of your net Vega and Theta exposure—lowering your breakeven hurdle dramatically.
- Respect the 3-Day Pre-Earnings Income Suppression Rule: Tempted to flip sides and sell naked options 24 hours before earnings to “harvest IV crush”? One 18% earnings shock can wipe out six months of income. That is why OptionMAV automatically suppresses
SELLCALLandSELLPUTwithin 3 days of earnings while highlighting cleaner 4–7 day pre-catalyst directional windows.
Want the full Earnings Season Playbook and VIX stress-test tables? Read Chapter 7 of our 201-page companion manual, The Greeks Are Not Your Enemy: The OptionMAV Playbook ($12.99 Kindle / $29.99 Paperback).
The 3 Categories of Retail Options Software (How to Choose the Right Tool)
Self-directed US stock & ETF options tools fall into three distinct architectural categories:
Helpful for drawing P&L curves after you already picked a ticker and strike—but offers zero automated market-wide contract discovery, zero hard IV Rank gating, and zero automated exit monitoring.
Streams dark-pool and sweep alerts ($576–$1,788/yr) without revealing whether an institution is hedging 500,000 shares of stock—leaving retail traders chasing noisy premium with no exit plan.
Computes all 8 Black-Scholes-Merton Greeks locally, enforces a hard 52-week IV Rank ≥ 50 income gate + 3-day pre-earnings guard, toggles 1-click vertical credit/debit spreads, and monitors exits with $0/mo ongoing USB fees.
Choose Your OptionMAV Setup — $0/mo Physical USB, Android App & Free Calculator
Screen US stock & ETF options contracts with all 8 Black-Scholes-Merton Greeks, rolling 52-week IV Rank (≥50 income gating), 3-day pre-earnings IV-crush protection, and one-toggle vertical credit/debit spreads—without surrendering your watchlist to a $200/month cloud platform.
Frequently Asked Questions
Why did my call option drop in value even though the stock went up?
Every option’s price combines intrinsic value and extrinsic value (time + implied volatility). If you bought when Implied Volatility was high—such as right before earnings—and IV falls sharply after the news, the Vega loss from falling volatility can outweigh the Delta gain from a modest stock rally.
How do vertical debit spreads reduce IV crush risk?
In a Call Debit Spread or Put Debit Spread, you buy a closer-to-the-money option and simultaneously sell a further out-of-the-money option in the same expiration. Because the short leg also loses value when IV drops, your net Vega exposure and entry cost are significantly reduced.
Continue Exploring the OptionMAV Options Research Library
- Best AI Options Screener Without a Monthly Subscription: OptionMAV $159 USB & Android App vs. $200/Mo Cloud Tools
- Vertical Credit & Debit Spread Screener: Find Defined-Risk Options Setups Without Level 4 Naked Margin
- IV Rank Options Screener (0–100) & Pre-Earnings IV Crush Guard: Stop Selling Cheap Options Premium
- Covered Call & Cash-Secured Put Screener: Run the Wheel Strategy Without Linking Your Brokerage Account
- Options Greeks Explained in Plain English (Delta, Theta, Vega, Vanna & Charm): The OptionMAV Playbook
- Stop Watching Winning Options Decay to Zero: Automated Options Exit Alerts, Roll Guidance & Android Portfolio Tracking
- OptionStrat Alternative: Visual Payoff Calculator vs. OptionMAV’s $0/Mo AI Options Screener & Spread Analyzer
- Unusual Whales & Cheddar Flow Alternative: Why Retail Traders Ditch Noisy Dark-Pool Sweeps for Defined-Risk AI Setups
- Market Chameleon & Barchart Options Screener Alternative: Own 52-Week IV Rank & Wheel Screening on a $159 USB
- Weekly vs. Swing vs. LEAPs Options: Complete Delta (0.20 vs. 0.50) & DTE Selection Matrix for Retail Traders
- Why DIY Options Spreadsheets & Weekend Scripts Break Down—And How a Turnkey $159 USB Solves All 8 Greeks Locally
Interactive Tools & Official Channels: 🧮 Free Spread & IV Rank Calculator · 📘 201-Page Greeks Playbook ($12.99) · ⚡ OptionMAV USB ($159 · $0/mo) · 🛒 Amazon US (#1 Ranked) · 📱 OptionMAV Android App · All 12 Guides