Direct Answer: Choosing the wrong expiration (DTE) and Delta ruins good stock picks: buying cheap 0.10 Delta Friday weeklies gives you a ~90% chance of expiring worthless, while selling 0.50 Delta puts takes stock-like drawdown for capped upside. OptionMAV maps setups across 4 editable Trading Profiles—targeting 0.40–0.55 Delta for directional buyers and 0.20–0.25 Delta (~1σ OTM) for income sellers across Weekly, Swing, Conservative, and LEAPs horizons.
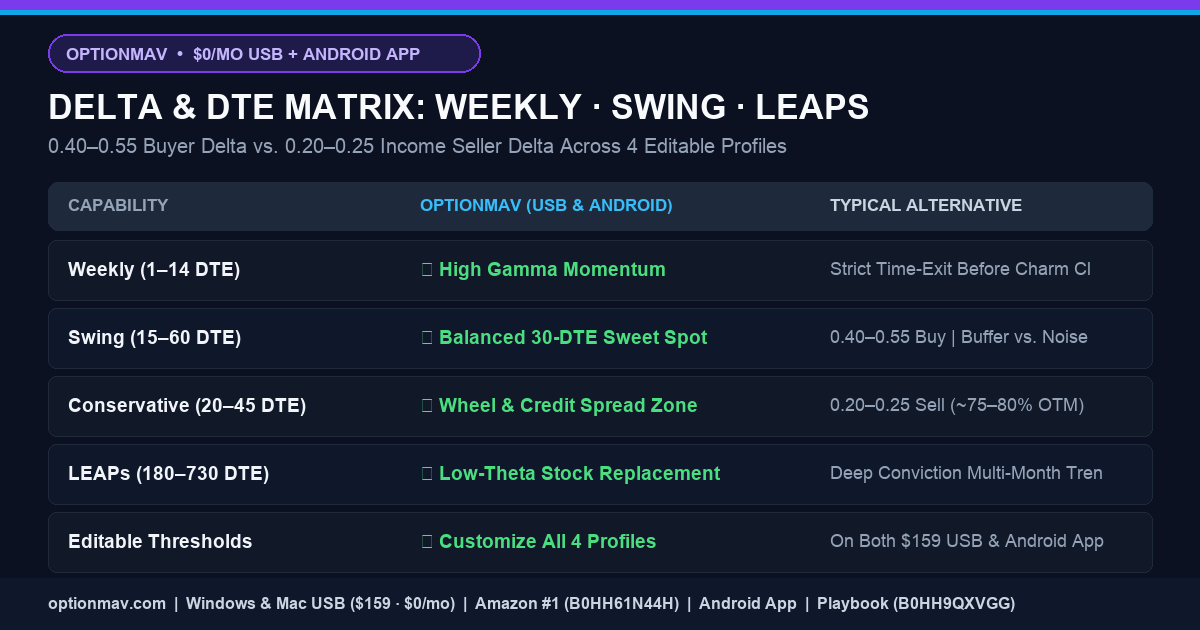
The Complete OptionMAV 4-Profile Delta & DTE Matrix
| OptionMAV Profile | Target DTE Window | Target Delta Zone | Dominant Greeks to Watch | Ideal Trader Use Case |
|---|---|---|---|---|
| 1. Weekly Tactical | 1 – 14 DTE | 0.45–0.55 Δ (Buyers) | High Gamma + steep Theta & Charm | Fast 1–4 day momentum bursts with tight profit/stop discipline—never held passively over long weekends. |
| 2. Swing / Monthly | 15 – 60 DTE | 0.40–0.55 Δ (Buyers) · 0.20–0.25 Δ (Sellers) | Balanced Delta + manageable Theta | Everyday trader sweet spot: gives a multi-week thesis breathing room without paying 12-month premium. |
| 3. Conservative / Income | 20 – 45 DTE | 0.20–0.25 Δ (~75–80% prob. OTM) | Positive Theta + IV Rank ≥ 50 Vega | Covered Calls, Cash-Secured Puts & Call/Put Credit Spreads targeting the 80% premium-decay exit rule. |
| 4. LEAPs Conviction | 180 – 730 DTE | 0.50–0.70 Δ | Low daily Theta + Vega / Rho | Capital-efficient long-term US equity & ETF positioning with minimal daily time-decay stress. |
Why 0.40–0.55 Buyer Delta Beats Both “Cheap Lotto OTM” and “0.90 Deep ITM”
- Why 0.08–0.15 Delta “Cheap” Contracts Fail: They look affordable at $0.45 ($45/contract), but high negative Charm bleeds their Delta overnight—requiring an explosive move immediately just to break even.
- Why 0.85–0.95 Deep-ITM Contracts Underperform on Short Swings: Wide bid-ask spreads and heavy capital tie-up sacrifice convexity while leaving hundreds of dollars per contract at risk on sudden gap-downs.
- Why 0.40–0.55 Delta Is the Inflection Sweet Spot: Maximum Gamma acceleration per dollar risked—so if your thesis is right, Delta climbs rapidly toward 0.70+, and if wrong, your predefined premium stop cuts risk cleanly.
Both the $159 OptionMAV USB (Windows & Mac) and the OptionMAV Android App let you switch between all 4 profiles in one click—or customize your own conviction, DTE, and risk thresholds.
The 3 Categories of Retail Options Software (How to Choose the Right Tool)
Self-directed US stock & ETF options tools fall into three distinct architectural categories:
Helpful for drawing P&L curves after you already picked a ticker and strike—but offers zero automated market-wide contract discovery, zero hard IV Rank gating, and zero automated exit monitoring.
Streams dark-pool and sweep alerts ($576–$1,788/yr) without revealing whether an institution is hedging 500,000 shares of stock—leaving retail traders chasing noisy premium with no exit plan.
Computes all 8 Black-Scholes-Merton Greeks locally, enforces a hard 52-week IV Rank ≥ 50 income gate + 3-day pre-earnings guard, toggles 1-click vertical credit/debit spreads, and monitors exits with $0/mo ongoing USB fees.
Choose Your OptionMAV Setup — $0/mo Physical USB, Android App & Free Calculator
Screen US stock & ETF options contracts with all 8 Black-Scholes-Merton Greeks, rolling 52-week IV Rank (≥50 income gating), 3-day pre-earnings IV-crush protection, and one-toggle vertical credit/debit spreads—without surrendering your watchlist to a $200/month cloud platform.
Frequently Asked Questions
What Delta is best for buying calls and puts versus selling Covered Calls or Credit Spreads?
For directional buyers (BUYCALL / BUYPUT), 0.40 to 0.55 Delta balances immediate responsiveness and Gamma acceleration without overpaying for deep-ITM contracts. For premium sellers (Covered Calls, Cash-Secured Puts, Credit Spreads), 0.20 to 0.25 Delta places the short strike roughly 1 standard deviation out-of-the-money (~75–80% probability of expiring OTM).
Can I customize DTE and risk rules inside OptionMAV?
Yes. OptionMAV ships with 4 pre-calibrated profiles (Weekly, Swing, LEAPs, and Conservative) and allows you to edit profile parameters locally on both the Windows & Mac USB and the Android App.
Continue Exploring the OptionMAV Options Research Library
- Best AI Options Screener Without a Monthly Subscription: OptionMAV $159 USB & Android App vs. $200/Mo Cloud Tools
- Vertical Credit & Debit Spread Screener: Find Defined-Risk Options Setups Without Level 4 Naked Margin
- IV Rank Options Screener (0–100) & Pre-Earnings IV Crush Guard: Stop Selling Cheap Options Premium
- Covered Call & Cash-Secured Put Screener: Run the Wheel Strategy Without Linking Your Brokerage Account
- Options Greeks Explained in Plain English (Delta, Theta, Vega, Vanna & Charm): The OptionMAV Playbook
- Stop Watching Winning Options Decay to Zero: Automated Options Exit Alerts, Roll Guidance & Android Portfolio Tracking
- OptionStrat Alternative: Visual Payoff Calculator vs. OptionMAV’s $0/Mo AI Options Screener & Spread Analyzer
- Unusual Whales & Cheddar Flow Alternative: Why Retail Traders Ditch Noisy Dark-Pool Sweeps for Defined-Risk AI Setups
- Market Chameleon & Barchart Options Screener Alternative: Own 52-Week IV Rank & Wheel Screening on a $159 USB
- Why Your Call Option Lost Money When the Stock Went Up: Plain-English Guide to Earnings IV Crush & the 3-Day Guard
- Why DIY Options Spreadsheets & Weekend Scripts Break Down—And How a Turnkey $159 USB Solves All 8 Greeks Locally
Interactive Tools & Official Channels: 🧮 Free Spread & IV Rank Calculator · 📘 201-Page Greeks Playbook ($12.99) · ⚡ OptionMAV USB ($159 · $0/mo) · 🛒 Amazon US (#1 Ranked) · 📱 OptionMAV Android App · All 12 Guides